IMPORTANT DISCLAIMER: This guide references the underwriting practices of commercial property insurers, including the COPE framework (Construction, Occupancy, Protection, Exposure); the ISO Public Protection Classification (PPC) and Fire Suppression Rating Schedule (FSRS) from Verisk (formerly Insurance Services Office); FM Global Property Loss Prevention Data Sheets; NFPA 101, NFPA 1, NFPA 25, NFPA 72, NFPA 13, NFPA 14, NFPA 20, and NFPA 10; the International Fire Code (IFC); and the requirements of individual property insurers and reinsurers. Underwriting methods, risk grading, loss-estimate definitions, and premium calculations vary by insurer, jurisdiction, and property type. Terms such as PML, MFL, and NLE are used differently by different insurers. This guide is a starting point only. Always verify requirements and available credits with your property insurer, your broker, and your Authority Having Jurisdiction (AHJ).
Insurance underwriting is how an insurer evaluates the risk of a property and sets the terms of coverage. For fire, the underwriter weighs the likelihood and severity of a loss, the adequacy of protection, and the potential for business interruption. The result is a decision: whether to insure, at what price, with what deductible, and under what conditions.
This guide explains how underwriters see a building and how to present it accurately and favorably. The goal is not to hide risk but to identify, manage, and document it. An underwriter who sees a well-controlled risk will usually offer better terms than one who sees an unknown.
This article covers the underwriter’s perspective, the COPE framework, loss estimates, valuation and coverage, business interruption, risk grading, the underwriting process, the insurer’s inspection, emerging hazards, and how designers and owners can prepare.
◆ Section 1: The Underwriting Perspective
An underwriter is not checking code compliance. Code sets a legal minimum for life safety; underwriting evaluates the probability and severity of financial loss. A building can be fully code-compliant and still be a poor insurance risk (for example, a combustible-storage warehouse protected only to code minimums).
A. What the Underwriter Wants to Know
| Question | Why It Matters |
|---|---|
| What is the building? | Construction, age, size, occupancy |
| What is the fire risk? | Hazard classification, fuel load, ignition sources |
| What protects the building? | Sprinklers, alarms, water supply, fire department |
| What is the exposure? | Adjacent buildings, wildfire, flood, external hazards |
| What is the loss potential? | PML, MFL, business interruption |
| How is the risk managed? | Maintenance, inspection, training, housekeeping, impairment control |
| Who runs the risk? | Management attitude, loss history, financial stability |
B. The Underwriter’s Constraints
Underwriters work within the insurer’s risk appetite, reinsurance treaties and capacity limits, regulatory requirements, and market competition. This is why two insurers can offer very different terms for the same building.
C. The Underwriter’s Decision
- Accept at standard terms
- Accept with conditions (e.g., sprinkler upgrade, fire watch, hot work controls)
- Accept at a higher premium or deductible
- Decline (the risk is outside appetite or capacity)
Key point: Underwriters evaluate risk to price it. The better the risk is understood and managed, the more favorable the terms.
Key Article: Article 149: Insurance Requirements and Fire Protection Credits
Pro Tip: The underwriter is not the enemy. A well-managed risk is a better outcome for both the insurer and the owner.
◆ Section 2: The COPE Framework
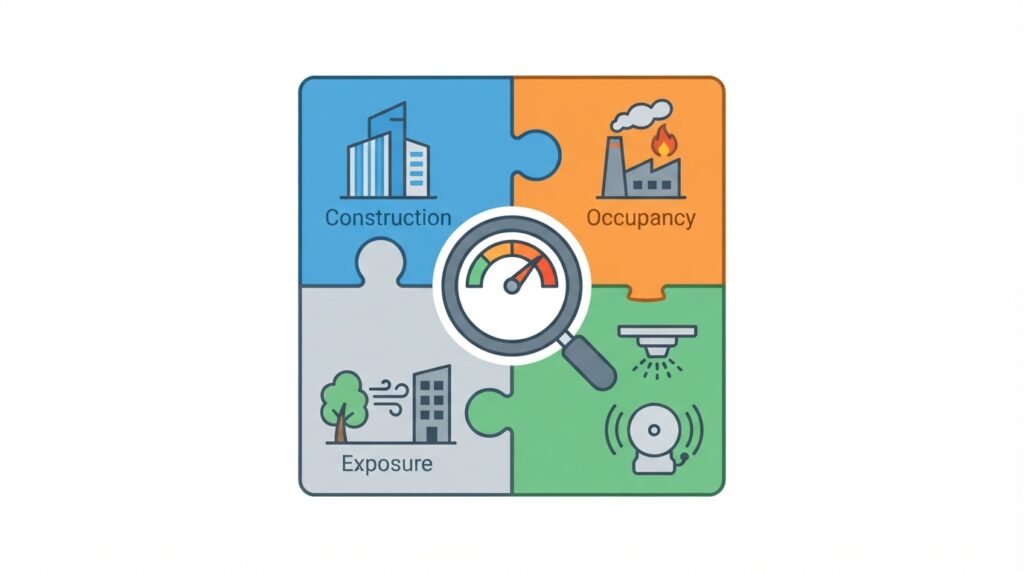
COPE is the foundation of property underwriting: Construction, Occupancy, Protection, and Exposure.
A. Construction
| Factor | Underwriter’s Concern |
|---|---|
| Building materials | Combustible vs. noncombustible; mass timber and wood-frame concerns |
| Fire-resistance rating | Structural fire resistance, fire-rated compartmentation |
| Roof assembly | Fire classification, wind resistance, rooftop equipment (e.g., PV) |
| Exterior walls and cladding | Combustible insulation or cladding, fire spread up the façade |
| Concealed spaces and openings | Fire spread through voids, unprotected shafts and penetrations |
| Age and condition | Deterioration, outdated wiring, deferred maintenance |
B. Occupancy
| Factor | Underwriter’s Concern |
|---|---|
| Use | What the building is used for, and by whom |
| Hazard classification | Light, ordinary, or extra hazard (NFPA 13); commodity class for storage |
| Combustible loading | Quantity, arrangement, and height of combustibles |
| Ignition sources | Hot work, electrical, heating, cooking, process equipment |
| Hazardous materials | Flammable liquids, gases, dusts, lithium-ion batteries |
| Housekeeping | Waste management, storage practices |
| Vacancy | Vacant or unoccupied buildings carry higher arson and undetected-fire risk |
C. Protection
| Factor | Underwriter’s Concern |
|---|---|
| Sprinkler system | Coverage, design vs. actual hazard, water supply, maintenance |
| Fire alarm | Detection, notification, off-site monitoring |
| Water supply | Reliability, adequacy, hydrants, mains, pressure, storage |
| Fire pump | Reliability, testing, power supply |
| Fire department | Response time, capability, staffing |
| Extinguishers | Placement, type, maintenance |
| Special hazard suppression | Clean agent, foam, CO₂, kitchen hood systems |
| Impairment control | Procedures when systems are out of service |
D. Exposure
| Factor | Underwriter’s Concern |
|---|---|
| Adjacent buildings | Fire spread potential, separation distance |
| Wildfire | Wildland-urban interface, embers, defensible space |
| Flood | Flood zone, storm surge |
| Wind | Hurricane, tornado |
| Seismic | Earthquake zone, post-earthquake fire |
| External hazards | Adjacent storage, vehicles, utilities, neighboring occupancies |
Key point: Each COPE factor contributes to the overall risk assessment. Strong protection can offset some construction or occupancy weaknesses, but it cannot offset poor management.
Pro Tip: Document your building’s COPE profile. It is the basis for the underwriter’s evaluation.
◆ Section 3: Loss Estimate Methods
Underwriters estimate the potential loss from a fire to set premium, decide capacity, and structure reinsurance. Terminology varies by insurer, so always ask how a specific insurer defines each term.
A. Probable Maximum Loss (PML)
PML is the largest loss likely from a single fire, assuming the fire protection functions as designed (and often assuming some degree of protection impairment or delayed response). It may be expressed as a percentage of total insured value or as a dollar amount.
| Factor | Consideration |
|---|---|
| Fire protection | Sprinklers, alarms, water supply |
| Construction | Fire resistance, compartmentation, fire walls |
| Occupancy | Hazard classification, fuel load |
| Exposure | Adjacent buildings and spread potential |
B. Maximum Foreseeable Loss (MFL)
MFL is the largest loss that could occur from a single fire if the active protection (typically sprinklers) fails or is unavailable, with passive features such as fire walls assumed to work. It is typically larger than PML.
C. Related Terms You May Encounter
| Term | General Meaning |
|---|---|
| Normal Loss Expectancy (NLE) | The expected loss with protection functioning and fire department response; used by FM Global |
| Maximum Possible Loss (MPL) | Total loss of a fire area or building, with all protection and compartmentation failing |
| Estimated Maximum Loss (EML) | Insurer-specific estimate of the largest realistic loss; definitions differ |
D. How Loss Estimates Are Used
| Use | Application |
|---|---|
| Underwriting | Determines premium and capacity offered |
| Reinsurance | Determines reinsurance needs |
| Risk management | Identifies the largest loss potentials |
| Capital allocation | Allocates capital to the largest risks |
| Owner planning | Informs protection investment and business continuity priorities |
Key point: The better the fire protection and compartmentation, the lower the loss estimate. Loss estimates include both property damage and business interruption.
Pro Tip: Ask your insurer or broker for your PML/MFL figures and the assumptions behind them. They drive your insurance cost and your risk-improvement priorities.
◆ Section 4: Valuation, Limits, and Coverage Structure
Fire protection earns credit only if the coverage itself is sound. Many owners are surprised by a loss because of how the policy was structured, not how the building burned.
| Topic | What to Understand |
|---|---|
| Insured values | Underinsurance leads to coinsurance penalties or limited recovery; revalue regularly |
| Valuation basis | Replacement cost vs. actual cash value |
| Ordinance or law coverage | Cost of rebuilding to current code (relevant to older buildings) |
| Deductibles | Higher deductibles lower premium but increase retained risk |
| Sublimits | Caps on specific items such as debris removal, extra expense, or specific perils |
| Protective safeguards conditions | Policy conditions requiring sprinklers, alarms, or other systems to be maintained in service |
| Vacancy provisions | Coverage may be limited or suspended after a set period of vacancy |
| Exclusions | Perils or conditions not covered |
Key point: Protective safeguards conditions are enforceable. If the policy requires a sprinkler system to be in service and it was impaired without notice, coverage can be reduced or denied.
Pro Tip: Review the policy conditions with your broker, not just the premium. Make sure your impairment procedures satisfy every protective safeguards requirement.
◆ Section 5: Business Interruption
Business interruption (BI) is often a larger loss than the physical damage. A small fire can stop operations for months if a critical area, piece of equipment, or utility is lost.
| Concept | Description |
|---|---|
| Period of restoration | Time to repair, rebuild, and resume operations |
| Lost revenue and continuing expenses | The basis of the BI loss |
| Extra expense | Costs to speed recovery or operate temporarily elsewhere |
| Critical equipment | Long-lead items such as turbines, transformers, and specialized machinery |
| Single points of failure | One room, line, or utility that stops everything |
| Contingent BI | Loss caused by a fire at a supplier or customer |
| Utility service interruption | Loss caused by an off-site utility outage |
Key point: Underwriters look for ways to shorten recovery: redundancy, spare parts, separation of critical operations, and a tested business continuity plan.
Pro Tip: Identify your single points of failure and document how you would recover from each.
◆ Section 6: Risk Grading and Rating
Underwriters use grading and rating systems to evaluate and price risk. It helps to separate three different things.
A. Community-Level Rating: ISO PPC
The ISO Public Protection Classification rates a community’s fire-suppression capability on a scale of 1 (best) to 10. It is based on the FSRS, which scores:
| Component | Maximum Points |
|---|---|
| Fire department | 50 |
| Water supply | 40 |
| Emergency communications | 10 |
| Community risk reduction | 5.5 |
The total is 105.5 points. The PPC applies to the community, not to your specific building, but it influences rates, particularly for smaller commercial and residential properties. Large industrial and commercial risks are typically priced more on property-specific engineering.
B. Property-Level Risk Grade
The risk grade is the insurer’s own qualitative or numerical assessment of your specific property. It may be expressed as A–F, a numeric score, or Low–Medium–High. Some insurers use engineering-based grading of “Highly Protected Risk” (HPR) status, which requires strong sprinkler protection, reliable water supply, and effective management of impairments and hazards. FM Global and other engineering-led insurers rate individual locations and issue loss-prevention recommendations.
C. The Rating
The rating is the quantitative calculation of premium, based on:
- The loss estimates (PML, MFL, NLE)
- The risk grade and COPE evaluation
- The insurer’s base rates and expenses
- Fire protection credits
- Loss history
- Deductible selection
- Market conditions and reinsurance cost
Key point: The ISO PPC is a community rating, and the risk grade is a property rating. Improve the part you control, which is your property.
Key Article: Article 149: Insurance Requirements and Fire Protection Credits
Pro Tip: Ask your broker exactly how your risk grade is determined. Understanding the factors lets you improve them.
◆ Section 7: The Underwriting Process
A. The Process Steps
| Step | Activity |
|---|---|
| 1. Submission | The broker submits the application and supporting information |
| 2. Review | The underwriter reviews the submission and asks questions |
| 3. Inspection | The insurer may order a physical engineering survey |
| 4. Risk assessment | The underwriter assesses COPE, loss estimates, and management quality |
| 5. Pricing | The underwriter determines the premium |
| 6. Quotation | The underwriter provides terms |
| 7. Negotiation | The broker and underwriter negotiate terms and conditions |
| 8. Binding | The policy is bound |
B. The Submission Package
- Application and statement of values
- Building description (COPE data)
- Fire protection description
- Loss history (typically 5 to 10 years)
- Risk management program
- Inspection and test reports
- Maintenance and impairment records
- Business continuity plan
- Description of recent improvements
C. The Quote
The quote includes the premium, deductible, limits and sublimits, conditions (including protective safeguards), and exclusions.
Key point: A complete, well-organized submission makes the underwriter’s job easier and produces better terms.
Pro Tip: Build the submission throughout the year, not in the weeks before renewal.
◆ Section 8: Preparing for Underwriting
A. The Narrative
A short narrative should explain what the building is, what the fire protection is, how the risk is managed, what the loss history is (including what was learned from any losses), and what improvements have been made.
B. Supporting Documentation
- Sprinkler, standpipe, and fire pump inspection and test reports (NFPA 25)
- Fire alarm test reports (NFPA 72)
- Extinguisher and fire door inspection records
- Special hazard system service records (kitchen, clean agent, foam)
- Impairment records and fire watch logs
- Hot work permit program records
- Training and drill records
- Emergency response plan
- Business continuity plan
C. Highlight Improvements
New sprinklers, a new alarm, a new roof, or upgraded water supply should be documented with dates, scope, and listings or approvals.
D. Preparation Checklist
| Item | Status |
|---|---|
| COPE profile documented | ☐ |
| Loss estimates (PML, MFL) obtained, if available | ☐ |
| Risk grade and its factors understood | ☐ |
| Statement of values current | ☐ |
| Building and fire protection descriptions prepared | ☐ |
| Loss history prepared, with corrective actions | ☐ |
| Inspection, test, and maintenance records current | ☐ |
| Impairment, hot work, and training records available | ☐ |
| Emergency response and business continuity plans available | ☐ |
| Open insurer recommendations tracked and responded to | ☐ |
| Improvements documented | ☐ |
| Broker engaged and renewal timeline planned | ☐ |
Key point: An undocumented system is hard for an underwriter to credit.
Pro Tip: Keep a single “insurance file” updated all year with test reports, recommendation responses, and improvement records.
◆ Section 9: The Insurer’s Inspection
The insurer’s inspection (often called an engineering or loss-control survey) verifies the submission and identifies issues.
A. What the Inspector Checks
| Area | What the Inspector Checks |
|---|---|
| Building | Construction, condition, housekeeping, compartmentation |
| Fire protection | Sprinkler coverage vs. hazard, valve supervision, alarm, extinguishers |
| Water supply | Hydrants, mains, tanks, pressure, fire pump reliability |
| Hazards | Hot work, electrical, flammable liquids, storage arrangements |
| Exposure | Adjacent buildings and external hazards |
| Management | Maintenance, impairment control, training, documentation |
B. The Inspection Report
The report typically includes observations, recommendations (often ranked by priority), a risk grade, and PML/MFL estimates.
C. Managing Recommendations
| Action | Why It Matters |
|---|---|
| Respond in writing to every recommendation | Shows management engagement |
| Set owners and target dates | Prevents drift |
| Document completion with evidence | Earns credit and closes the item |
| Explain in writing where you disagree or cannot comply | Lets the insurer consider alternatives |
| Track open items to the next renewal | Unresolved items can affect terms or lead to conditions |
Key point: Insurers track whether recommendations are completed. A history of closing recommendations builds credibility; a history of ignoring them can lead to conditions or non-renewal.
Pro Tip: Treat the inspection as a chance to demonstrate your fire protection and management program.
◆ Section 10: Emerging and Evolving Hazards
Underwriters are paying growing attention to hazards that existing codes and older rating methods may not fully address.
| Hazard | Underwriter’s Concern |
|---|---|
| Lithium-ion batteries and energy storage | Thermal runaway, difficulty of suppression, large concentrations in warehouses and data centers |
| Rooftop solar PV | Roof fire spread, firefighter access, rapid shutdown |
| Electric vehicle charging and parking | Vehicle fire severity, charging equipment, parking garage protection |
| Mass timber and combustible construction | Exposed timber, construction-phase fire risk |
| Combustible cladding and insulation | Vertical fire spread, rapid exterior fire growth |
| Hydrogen and alternative fuels | Gas release, ignition, specialized protection |
| High-piled and plastic storage | Fire severity beyond standard sprinkler design |
| Wildfire and climate-driven exposures | Embers, defensible space, changing risk zones |
| Construction, renovation, and demolition | Hot work, temporary protection impairments, vacancy |
Key point: Insurers may impose conditions or limits on these hazards before code catches up. Early dialogue with the insurer avoids surprises.
Pro Tip: If you plan new battery storage, solar, or alternative fuel systems, talk to your insurer before design is finalized.
◆ Section 11: Designing for Insurability
Architects and engineers influence insurability long before the first underwriting submission. Early design decisions affect PML, MFL, and premium for the life of the building.
| Design Decision | Insurance Benefit |
|---|---|
| Full sprinkler coverage designed to the actual hazard (not just minimum code) | Lower loss estimates and potential credits |
| Redundant, reliable water supply | Better protection reliability |
| Fire walls and compartmentation separating critical operations | Lower PML and shorter business interruption |
| Noncombustible or protected construction | Better construction rating |
| Separation from exposures | Reduced external fire spread |
| Protected, accessible critical equipment and utilities | Faster recovery |
| Documented commissioning and integrated testing | Evidence that systems work |
| Provision for maintenance access and inspection | Better long-term reliability |
Key point: Coordinate early with the owner’s broker or insurer. Insurers may require design features beyond code, such as FM Global-approved equipment or data-sheet criteria.
Pro Tip: Ask the owner’s insurer for its design requirements at concept stage, not at final approval.
◆ Section 12: Common Challenges and Mistakes
| Challenge or Mistake | Why It Happens | Solution |
|---|---|---|
| Incomplete submission | Not prepared | Prepare a complete package early |
| Fire protection not documented | No records | Maintain inspection and test records |
| Housekeeping or maintenance problems | Deferred upkeep | Implement a maintenance and housekeeping program |
| Unmanaged impairments | No impairment procedure | Implement a documented impairment program and notify the insurer |
| Inspection recommendations ignored | No owner assigned | Track and close recommendations |
| Improvements not highlighted | Not documented | Present improvements with evidence |
| Risk grade lower than expected | Factors not understood | Ask how the grade is determined |
| Underinsurance | Values outdated | Revalue regularly |
| Business interruption not analyzed | Focus on property only | Analyze critical dependencies |
| Broker engaged too late | Rush at renewal | Engage the broker early |
| Policy conditions not understood | Only premium reviewed | Review protective safeguards and exclusions |
Key point: Most underwriting problems are documentation and management problems, not technical ones.
Pro Tip: Work with your broker. A good broker understands how underwriters think and can help you prepare.
◆ Section 13: Conclusion
Insurance underwriting is the process by which an insurer evaluates a property’s risk and sets the terms of coverage. Underwriters use the COPE framework, loss estimates (PML, MFL, NLE), and risk grading to assess and price that risk, while also considering valuation, business interruption, and management quality.
The critical elements are:
- COPE framework: construction, occupancy, protection, exposure
- Loss estimates: PML, MFL, and business interruption
- Coverage structure: values, limits, deductibles, and protective safeguards
- Risk grading: property-level grade vs. community-level ISO PPC
- Submission package: complete, organized, and current
- Documentation: evidence of protection and management
- Inspection and recommendations: verification and follow-through
- Emerging hazards: early dialogue with the insurer
- Broker: the intermediary who understands the process
The most common failure is an incomplete submission. An underwriter cannot give credit for what is not documented.
Key Takeaways
- Underwriting evaluates risk to price it; better-managed risks get better terms.
- COPE (Construction, Occupancy, Protection, Exposure) is the foundation.
- PML, MFL, and NLE are defined differently by different insurers, so ask for the definitions.
- Underinsurance and unmet protective safeguards conditions can undermine coverage.
- Business interruption can exceed the property loss.
- ISO PPC rates the community; the risk grade rates your property.
- A complete, well-organized submission produces better outcomes.
- Respond to and close insurer recommendations.
- Emerging hazards such as batteries, solar, and EV charging need early insurer dialogue.
- Design decisions made early affect insurability for the life of the building.
Take Action Today
- Document your building’s COPE profile.
- Obtain your PML/MFL figures and their assumptions.
- Understand your risk grade and what drives it.
- Review insured values, valuation basis, and protective safeguards conditions with your broker.
- Identify your business interruption single points of failure.
- Maintain fire protection, maintenance, impairment, and training records.
- Track and close all insurer recommendations.
- Highlight recent improvements with evidence.
- Prepare for the insurer’s inspection.
- Engage your broker early and plan the renewal timeline.
Continue Reading from Our Series
- Related guide: Article 167, Fire Safety Liability and Legal Precedents
- Related guide: Article 149, Insurance Requirements and Fire Protection Credits
- Read more: Article 169, Fire Investigation Standards (NFPA 921) (planned)
About This Guide: This article is part of a series on commercial building fire safety, written for facility managers, architects, and code officials. It references model codes and standards for educational purposes. Always consult your local AHJ, your insurer, and your broker for project-specific requirements.